☎ Call Today
Criminal Defense • Frisco, Texas
Serving 9 DFW Counties — Collin • Dallas • Denton • Tarrant • Rockwall • Kaufman • Ellis • Johnson • Hunt — Available 24/7
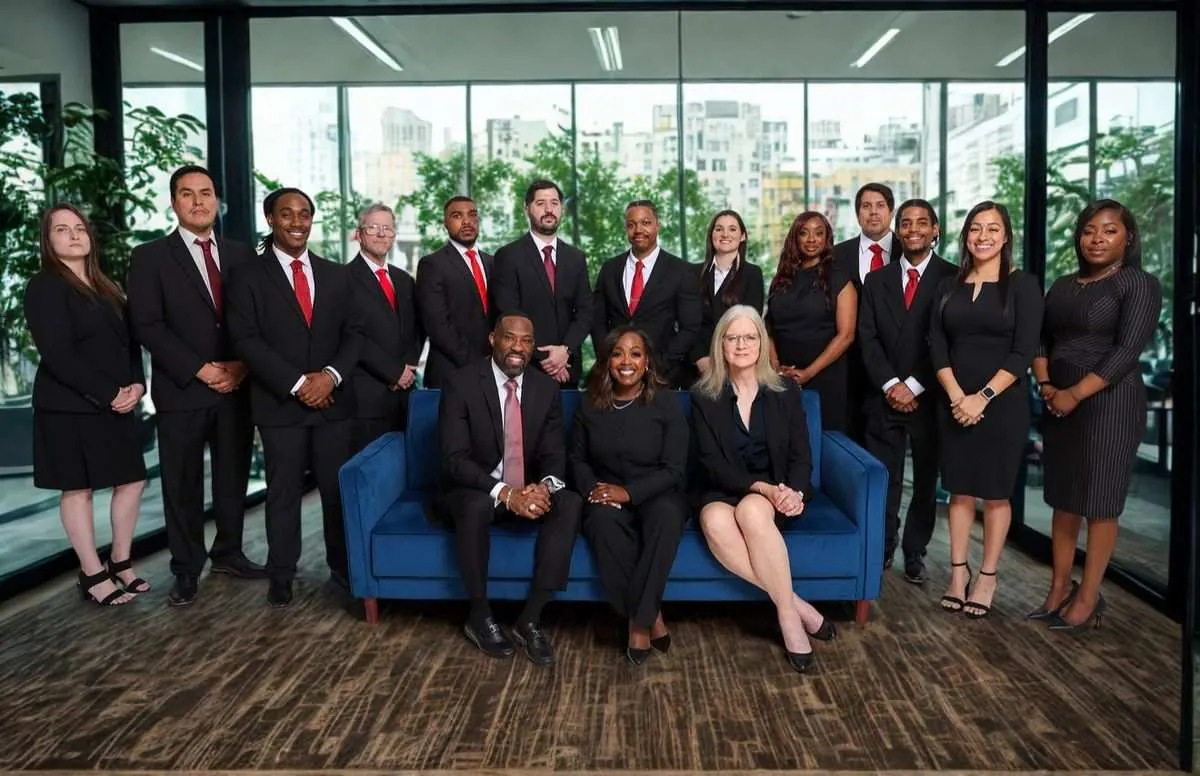
The L and L Law Group team at our Frisco, Texas office — co-founding partners Reggie London and Njeri London with staff
Our Frisco officeEst. 2011
The L and L Law Group team·Frisco, Texas
White Collar & Fraud · Insurance Fraud

Texas insurance fraud defense

In Texas, insurance fraud is prosecuted under Penal Code § 35.02 and graded by the value of the fraudulent claim — from a Class C misdemeanor up to a first-degree felony carrying 5 to 99 years or life. These cases are built from your own claim file long before any arrest. L and L Law Group defends claim, application, and provider-kickback cases across Collin, Denton, Dallas, and Tarrant Counties.

A Texas insurance fraud charge under Penal Code § 35.02 is value-graded — a Class C misdemeanor under $100 climbing to a first-degree felony at $300,000 or more, with insurance application fraud a flat state jail felony at any amount and any act risking death or serious bodily injury a first-degree felony regardless of the dollar figure. The offense is complete the moment a knowingly false, material statement is presented to an insurer with intent to defraud — payment is not an element, so a denied or still-pending claim is chargeable the same as a paid one. Conviction carries mandatory restitution to the carrier under § 35.02(e), including its court costs and attorney's fees, plus a crime-of-dishonesty tail that reaches professional licensing, firearm rights under Penal Code § 46.04, and immigration status. The two soft spots every case shares — whether any statement was knowingly false about something material, and whether the State can prove intent to deceive rather than a good-faith disagreement about a number — are the operative battleground in DFW county courts.

insurance fraud: Texas punishment ranges by value of the fraudulent claim
Value of fraudulent claimOffense levelConfinementMax fine
Under $100Class C misdemeanorNone (fine-only)$500
$100 – under $750Class B misdemeanorUp to 180 days, county jail$2,000
$750 – under $2,500Class A misdemeanorUp to 1 year, county jail$4,000
$2,500 – under $30,000State jail felony180 days – 2 years, state jail$10,000
$30,000 – under $150,000Third-degree felony2 – 10 years, TDCJ$10,000
$150,000 – under $300,000Second-degree felony2 – 20 years, TDCJ$10,000
$300,000+ — or any act risking death/serious bodily injuryFirst-degree felony5 – 99 years or life, TDCJ$10,000
Application fraud — any amount (§ 35.02(a-1), (d))State jail felony180 days – 2 years, state jail$10,000

Grades per Tex. Penal Code § 35.02(c) (brackets last reset Sept. 1, 2015). Under § 35.02(g) the value is reduced to the fraudulent portion only where a valid covered loss is proven; aggregation under § 35.03 can raise the grade. Conviction carries mandatory restitution to the insurer under § 35.02(e).

12 min read 2,900 words Reviewed June 20, 2026 By Reggie London
Direct Answer

A Texas insurance fraud charge under Penal Code § 35.02 is graded by the value of the fraudulent claim, running from a Class C misdemeanor under $100 to a first-degree felony at $300,000 or more; insurance application fraud is a flat state jail felony at any amount, and any act risking death or serious bodily injury is a first-degree felony regardless of value. The State must prove a statement made to an insurer, that the statement was false or misleading, that the false information was material under § 35.015, that the accused knew it was false, and that the accused intended to defraud or deceive — and payment of the claim is not an element. Defense work hinges on attacking knowledge and intent, the valid-portion offset under § 35.02(g) that limits the grade to the fraudulent slice, materiality failures, suppression of compelled or custodial statements, and the difference between a criminal lie and a good-faith valuation dispute. Because it is a crime of dishonesty, the collateral consequences — professional licensing discipline, firearm-rights loss, immigration exposure, mandatory restitution under § 35.02(e), and civil suits — demand careful defense planning from the first interview.

Free case review
Key Takeaways
  • Value-graded under PC § 35.02 — Class C misdemeanor under $100 up to a first-degree felony at $300,000+; application fraud is a flat state jail felony.
  • Two contested axes: whether any statement was knowingly false about a material fact, and whether the State can prove intent to defraud rather than a valuation disagreement.
  • Payment is not an element — a denied, withdrawn, or pending claim is chargeable the same as a paid one under § 35.02(a).
  • The valid-portion fight under § 35.02(g) and Florez v. State limits the grade to the fraudulent slice — documenting the legitimate loss can drop a felony a level.
  • Crime-of-dishonesty tail — licensing discipline, firearm-rights loss, immigration consequences, and mandatory restitution to the insurer under § 35.02(e).
Quick Case Review · 24/7

Get a free review

Direct to attorney — no call center. Most clients hear back within an hour.

By submitting, you agree to our Privacy Policy. No attorney-client relationship is formed until a written engagement is signed.

Texas Bar
Licensed since 2004
TXND · TXED
Federal Court Admitted
4.8 ★
Google Reviewed
9 DFW
Counties Served
24/7
Direct-to-Attorney Line
40+
Years Combined
Texas Bar Licensed TXND & TXED Federal 24/7 Jail Release Se Habla Español
Texas Legal Context

What the statute actually requires

Controlling statute Texas Penal Code § 35.02
Analytical framework Texas insurance fraud under Penal Code § 35.02 is value-graded — a Class C misdemeanor under $100 up to a first-degree felony at $300,000 or more — and requires proof that a statement to an insurer was knowingly false about a material fact, made with intent to defraud. Payment of the claim is not an element. The defining battles are knowledge and intent, the valid-portion offset under § 35.02(g) and Florez v. State, materiality under § 35.015, and the suppression of compelled or custodial statements drawn from the claim file.
5 Texas-specific insights
  1. The case is built from your own claim file. By the time a client learns he is a suspect, the carrier's special investigations unit has typically spent months assembling recorded interviews, an examination under oath compelled by the policy's cooperation clause, scene inspections, and database comparisons — all drawn from the claim. Under Insurance Code Chapter 701 that file is forwarded to the Texas Department of Insurance Fraud Unit, and by then the State's exhibit list is largely the client's own words. Anything said to an adjuster is a "statement" under § 35.01(3) and chargeable.
  2. Only the fraudulent slice should set the grade. Under § 35.02(g), where the accused proves by a preponderance that part of a claim came from a valid covered loss, the value of the claim is the total minus the valid portion. The Fort Worth Court of Appeals held in Florez v. State, No. 02-16-00195-CR (Tex. App.—Fort Worth June 8, 2017, no pet.) (mem. op.), that the value means the fraudulent portion only. A $40,000 hail claim with $3,000 of padding is a state-jail-felony number — but only if the legitimate $37,000 is documented and proven.
  3. Payment is not an element. Nothing in § 35.02 requires that a claim be paid, so a denied, withdrawn, or still-pending claim is chargeable on the same footing as one paid in full. "The company never lost a dollar" is therefore not a defense to guilt — though, used correctly, it is real leverage in negotiation.
  4. The kickback provision needs no false statement. Subsection (b) of § 35.02 criminalizes soliciting, offering, paying, or receiving a benefit in connection with goods or services for which an insurance claim is submitted — no false statement required. It is how prosecutors charge clinics, chiropractors, body shops, roofers, and case runners. Providers also face a rebuttable presumption under § 35.02(h) that whoever submitted a bill caused the claim to be presented.
  5. Intent is proven by circumstantial evidence. Intent to defraud is almost never proven by a confession. Texas courts allow it to be inferred from conduct, and the standard is generous to the State: the Obigbo court explained that intent to defraud and deceive may be proved by circumstantial evidence and that a jury may infer criminal intent from all the circumstances. Obigbo v. State, 6 S.W.3d 299, 305 (Tex. App.—Dallas 1999, pet. ref'd). Timing, inconsistencies, and financial pressure become the proof — which is why the pre-referral investigation is so dangerous.

How L and L Law Group defends an insurance fraud case

An insurance fraud accusation is unusual because the evidence already exists before anyone decides to prosecute. We get in front of the carrier's file before it hardens into an indictment and attack the two soft spots every § 35.02 case shares: knowing falsity about something material, and intent to deceive.

An insurance fraud accusation is unusual among criminal charges because the evidence already exists before anyone decides to prosecute. By the time you learn you are a suspect, the carrier's special investigations unit has typically spent months assembling recorded interviews, an examination under oath, scene inspections, and database comparisons — all drawn from your own claim. Our job is to get in front of that file before it hardens into an indictment, and to attack the two soft spots every § 35.02 case shares: whether any statement was knowingly false about something that mattered, and whether the State can prove you meant to deceive rather than merely disagree about a number.

We start by mapping the claim back to its source documents — the proof of loss, the estimates, the invoices, the recorded calls — and separating what you actually said from what a contractor, public adjuster, or billing clerk put in front of you to sign. Then we build the record of the legitimate loss, because Texas law puts that burden on the defense and rewards it directly at sentencing. From there the strategy splits depending on posture: a pre-charge investigation calls for quiet advocacy with the screening prosecutor; a returned indictment calls for a hard look at how the charged "statement" is described and what the discovery file actually shows. Co-founding partners Reggie London and Njeri London handle these matters directly rather than passing them to a screener, and the firm defends claim, application, and provider-kickback cases across the four DFW counties from its single Frisco office. For where this offense sits in the larger fraud landscape, see our white collar and fraud defense overview; for the neutral statutory reference, see the insurance fraud charge encyclopedia entry.

What counts as insurance fraud in Texas?

Texas Penal Code § 35.02 reaches three kinds of conduct: a false statement supporting a claim (subsection (a)), a false statement on a policy application (subsection (a-1)), and the kickback provision (subsection (b)), which needs no false statement at all. The insurer's loss is not an element.

Claim fraud — § 35.02(a)
Presenting — or causing someone to present — a statement you know is false or misleading in support of a claim for payment under an insurance policy, with intent to defraud or deceive the insurer. This is the familiar scenario and the most commonly charged subsection.
Application fraud — § 35.02(a-1)
Applying the same logic to a policy application rather than a claim. Under § 35.02(d) application fraud is a flat state jail felony regardless of any dollar amount, which is why it is graded separately from the value ladder.
The kickback provision — § 35.02(b)
Soliciting, offering, paying, or receiving a benefit in connection with goods or services for which an insurance claim is submitted. This provision needs no false statement at all, and it is how prosecutors charge clinics, chiropractors, body shops, roofers, and case runners inside organized-claim investigations.
"Statement" — § 35.01(3)
Any oral or written communication, record, or documented representation of fact made to an insurer — a definition that expressly captures computer-generated information. A recorded call to a claims line, a text to an adjuster, an entry in an online portal, an emailed invoice, and a signed proof-of-loss form are all "statements." Obigbo v. State, 6 S.W.3d 299, 309 (Tex. App.—Dallas 1999, pet. ref'd), confirmed that, where the Legislature has not narrowly defined a term, jurors give it the broadest meaning the context allows.

The companion term "insurance policy" is just as wide under § 35.01(1), sweeping in surety and cash bonds, benefit plans, and motor-club service plans alongside ordinary auto, home, health, and commercial coverage. One feature surprises nearly every client: the insurer's loss is not an element. Nothing in § 35.02 requires that a claim be paid, so a claim that was denied, withdrawn, or still under review when investigators arrived is chargeable on the same footing as one that paid in full. "The company never lost a dollar" is therefore not a defense to guilt — though, used correctly, it is real leverage when we negotiate.

What are the penalties for insurance fraud in Texas?

Punishment tracks the value of the fraudulent claim on the same dollar ladder Texas uses for theft — from a fine-only Class C misdemeanor up to a first-degree felony at $300,000 or more. Three grading rules — the valid-portion offset, the death-or-injury bump, and aggregation — decide more cases than the brackets do.

Punishment tracks the value of the claim on the same dollar ladder Texas uses for theft — a design the appellate courts have traced to deliberate legislative choice. The current brackets, last reset effective September 1, 2015, run from a fine-only misdemeanor to a first-degree felony, as set out in the punishment-range table at the top of this page.

Three grading rules decide more of these cases than the brackets do. The first is that only the fraudulent slice of a claim should set the grade. The Fort Worth Court of Appeals put it plainly: under § 35.02(g), where an accused proves by a preponderance that part of a claim came from a valid covered loss, "the 'value of the claim' is equal to the difference between the total claim amount and the amount of the valid portion of the claim" — in other words, "the 'value of the claim' means the fraudulent portion of the claim." Florez v. State, No. 02-16-00195-CR, slip op. at 3 (Tex. App.—Fort Worth June 8, 2017, no pet.) (mem. op., not designated for publication). A $40,000 hail claim with $3,000 of padding is a state-jail-felony number, not a third-degree number — but only if the legitimate $37,000 is documented and proven. The second rule overrides every dollar figure: under § 35.02(c)(7)(B), any act committed in connection with the offense that places a person at risk of death or serious bodily injury makes the case a first-degree felony no matter how small the claim, which is why staged collisions are charged at the top of the ladder. The third, § 35.03, lets the State combine separate claims made under one scheme — either by aggregating the values or, with three or more claims, bumping the grade one level above the most serious single claim. The two mechanisms are mutually exclusive, so an indictment that stacks both has a defect worth litigating.

Conviction also carries a financial tail most offenses lack. Section 35.02(e) makes restitution to the affected insurer mandatory and expressly includes the carrier's court costs and attorney's fees, and § 35.02(f) allows the same conduct to be prosecuted under Chapter 35, another statute such as theft or arson, or both. For the full sentencing picture across offense levels, our Texas punishment ranges guide lays out each grade in detail.

How the State proves intent — and where it breaks down

For a claim count under § 35.02(a) the State must prove five things beyond a reasonable doubt: a qualifying statement, falsity, materiality under § 35.015, knowledge, and intent to defraud. Intent is the battleground, and it is almost always proven by circumstantial evidence rather than a confession.

For a claim count under § 35.02(a), the State must prove five things beyond a reasonable doubt:

A qualifying statement
A communication, record, or documented representation of fact made to an insurer under § 35.01(3). The charge must attach to an identifiable statement — a specific form, recorded interview, invoice, or portal entry. A vague allegation that "the claim was fraudulent" with no pinned-down false statement is exposed.
Falsity
Measured against fact, not opinion. A genuine estimate, a value the policyholder believed, or a figure supplied by a third party the policyholder reasonably trusted is not "false" unless the State proves the accused knew otherwise.
Materiality — § 35.015
The false information must have been capable of affecting coverage eligibility, the amount payable, or the decision to issue the policy. The Obigbo court added a wrinkle for the State's benefit: the statute's list of examples of "material" information is illustrative, because "the word 'includes' is a term of enlargement and not of limitation." Obigbo, 6 S.W.3d at 308. Even so, a misstatement that could not have moved the payment decision fails the element.
Knowledge
The accused must have known the statement was false or misleading when it was made. Honest mistake, faulty memory about a date or serial number, and reliance on someone else's paperwork all attack this element head-on.
Intent to defraud or deceive
The highest culpable mental state in the chapter, and the battleground in most contested cases.

Intent is almost never proven by a confession. Texas courts allow it to be inferred from conduct, and the standard is generous to the State: in an insurance fraud appeal the court explained that "the elements of the offense, including intent to defraud and deceive, may be proved by circumstantial evidence" and that a jury "may infer criminal intent from all the circumstances." Obigbo, 6 S.W.3d at 305. Timing, inconsistencies, financial pressure, and what the accused told whom become the proof. That is precisely why the carrier's pre-referral investigation is so dangerous: the special investigations unit gathers recorded interviews, examinations under oath compelled by the policy's cooperation clause, photo metadata, and industry-database comparisons, and by the time the file reaches the Texas Department of Insurance Fraud Unit under Insurance Code Chapter 701, the State's exhibit list is largely your own words. Treat anything you say to an adjuster as a statement to law enforcement, because § 35.01(3) makes it chargeable and Chapter 701 makes it forwardable. The State also gets a statutory head start against providers: under § 35.02(h), a person who submitted a bill in support of a claim is rebuttably presumed to have caused the claim to be presented — a presumption that can be answered, but only with evidence.

Penalty and collateral consequences beyond the sentence

A fraud conviction is a crime of dishonesty, and the paperwork follows you long after any sentence ends — professional-licensing discipline, firearm-rights loss, immigration exposure as a crime involving moral turpitude, mandatory restitution to the insurer, and industry claim databases that outlive the court file.

A fraud conviction is a crime of dishonesty, and the paperwork follows you long after any sentence ends. Licensed insurance agents and adjusters face Texas Department of Insurance discipline independent of the criminal court. Physicians, chiropractors, and nurses pulled into a § 35.02(b) billing case face parallel licensing-board proceedings in which the criminal disposition becomes the central exhibit. A felony conviction strips firearm rights under Penal Code § 46.04 and federal law (18 U.S.C. § 922(g)(1)). For non-citizens, fraud convictions are generally crimes involving moral turpitude, and a fraud offense with a victim loss over $10,000 is an aggravated felony under federal immigration law — among the most serious removal categories that exist. Padilla v. Kentucky, 559 U.S. 356 (2010), requires defense counsel to advise non-citizen clients of these consequences before any plea, and the advice must be specific to the actual offense and the client's actual status.

Add employment screening for banking, bonding, and fiduciary roles, the insurer's civil suit and possible policy rescission, and industry claim databases that outlive the court file, and the cheapest-looking plea can become the most expensive decision in the case. Mapping those consequences — and the expunction or nondisclosure path that may follow a favorable resolution — belongs at the front of the case, not the end. A dismissal or acquittal can support expunction; a deferred-adjudication discharge may support an order of nondisclosure; a final felony conviction forecloses both, which is one more reason the early posture of the case matters so much.

DFW county court practice — where these cases are heard

Insurance fraud is filed in the ordinary criminal courts of the county where the claim conduct occurred — Collin, Dallas, Denton, and Tarrant — and the local docket shapes strategy. We defend these cases in all four counties, plus Rockwall, Kaufman, Ellis, and Hunt, from our single Frisco office.

Insurance fraud is filed and heard in the ordinary criminal courts of the county where the claim conduct occurred, and the local docket shapes strategy.

Collin County

Felony cases are indicted and heard in the district courts at the Collin County Courthouse (the Russell A. Steindam Courts Building) at 2100 Bloomdale Road in McKinney; misdemeanor grades go to the county courts at law in the same building. Collin juries are drawn from Frisco, Plano, McKinney, and Allen — document-literate panels that follow paper trails closely, which rewards a defense built on the client's own records. Many of our Frisco and Plano clients fall in this county.

Dallas County

Dallas County felony dockets run out of the Frank Crowley Courts Building on Riverfront Boulevard, with misdemeanors in the county criminal courts there as well. The county's volume means TDI referrals share space with a heavy violent-crime docket, and intake prosecutors retain discretion — so a well-documented presentation before indictment can influence whether a borderline file is charged as filed, reduced, or declined. See our Dallas criminal defense page.

Denton County

Cases file at the Denton County Courts Building in Denton. The county's suburban property-claim mix — roofs, vehicles, water losses — makes contractor-driven supplements a recurring fact pattern, which puts the knowledge element front and center. See our Denton County page.

Tarrant County

Fort Worth's Tim Curry Criminal Justice Center houses both the felony district courts and the misdemeanor courts. As elsewhere, restitution posture matters early: arriving at the first setting with a concrete accounting of the legitimate loss changes the tone of the conversation. See our Fort Worth page.

We defend insurance fraud cases in all four counties — and in Rockwall, Kaufman, Ellis, and Hunt — from our single office at 5899 Preston Road, Suite 101, in Frisco. We do not maintain branch offices in Dallas, Fort Worth, or Denton; we appear in those courts and defend those cases from Frisco. Once a case is filed, magistration under Code of Criminal Procedure article 15.17 brings the bail decision within roughly 48 hours, felony grades go to a grand jury for indictment, and discovery under article 39.14 reaches the entire claim file, the unit workup, and the referral packet — meaning the defense gets to audit the investigation that built the case. Our guide to fighting a charge and our bond conditions overview walk through each stage in plain English.

Key legal terms

Five terms decide most insurance fraud cases: the offense itself under § 35.02, the broad "statement" definition under § 35.01(3), materiality under § 35.015, the value-of-the-claim offset under § 35.02(g), and the provider presumption under § 35.02(h).

Insurance Fraud — § 35.02
Knowingly presenting a false or misleading material statement to an insurer with intent to defraud, in support of a claim or application — or, under subsection (b), paying or receiving a benefit tied to goods or services billed to an insurer.
Statement — § 35.01(3)
Any oral or written communication, record, or documented representation of fact made to an insurer — expressly including computer-generated information such as portal entries and recorded calls.
Materiality — § 35.015
A false statement is material if it could have affected coverage eligibility, the amount payable, or the decision to issue the policy. The test is objective and possibility-based.
Value of the Claim — § 35.02(g)
The figure that sets the punishment grade. Where the accused proves a valid covered loss by a preponderance, the value drops to the fraudulent portion only — the total claim minus the legitimate part.
Provider Presumption — § 35.02(h)
A rebuttable presumption that a person who submitted a bill in support of a claim caused that claim to be prepared or presented — aimed at providers who later blame a billing department.

These five terms recur in nearly every § 35.02 case, and each is a place where a careful defense can change the outcome — by pinning the State to a specific statement, by testing whether the misstatement was truly material, by documenting the legitimate portion of the loss, or by answering the provider presumption with evidence. For a wider vocabulary of Texas criminal-law terms, see our legal glossary.
Defense Strategy

What we evaluate first

A handful of defense levers do most of the work in Texas insurance fraud cases. We evaluate every one before charting a path — knowledge and intent first, then the valid-portion offset, materiality, suppression, and the valuation-dispute framing together set the strategy.

  1. No knowing falsity
    Policyholders sign what contractors, public adjusters, and billing staff hand them. If an inflated scope or an upcoded billing entry originated with someone else and the client did not know it was wrong, the knowledge element fails — and the § 35.02(h) presumption about who "caused" a bill to be presented says nothing about knowledge or intent. The defense maps each charged statement back to its source document and separates what the client actually said or signed from what a third party prepared. Obigbo v. State, 6 S.W.3d 299 (Tex. App.—Dallas 1999, pet. ref'd), confirms that knowledge of falsity is the State's burden.
  2. Valuation dispute, not a crime
    Disagreements over depreciation, actual cash value, scope of repair, or pre-existing damage are coverage arguments the civil system resolves every day. Treating a contested number as a criminal lie criminalizes negotiation, and juries grasp the difference. The defense frames the case as a good-faith disagreement about a figure rather than a knowing misrepresentation, using the carrier's own estimate range, the contractor's documentation, and industry pricing data to show the disputed amount was within a defensible range.
  3. Materiality failure under § 35.015
    Under § 35.015 the misstatement must have been capable of affecting coverage eligibility, the amount payable, or the decision to issue the policy. A wrong date, an address error, or a detail that could not have moved the payment decision does not satisfy the element. The defense isolates the specific statement the State calls false and tests whether it was objectively capable of affecting the carrier's decision — a possibility-based but real limit on what counts as criminal.
  4. The valid-portion fight under § 35.02(g)
    Even where some padding occurred, § 35.02(g) and Florez v. State, No. 02-16-00195-CR (Tex. App.—Fort Worth June 8, 2017, no pet.) (mem. op.), mean the grade reflects only the fraudulent slice. Proving the legitimate loss by a preponderance can pull a third-degree felony down to a state jail felony or a misdemeanor, which shifts probation eligibility, record-clearing options, and bargaining posture at once. The trap to avoid is the all-or-nothing defense: in Florez the defendant insisted the entire claim was valid, and the court held the § 35.02(g) instruction was therefore unavailable.
  5. No intent to defraud
    Where the timeline, the financial picture, and the client's cooperation read as an honest claim, the State's inference case thins. Prompt corrections, voluntary supplements, and openness with the adjuster all cut against deceit. Because intent to defraud is the highest culpable mental state in the chapter and is almost always proven circumstantially under Obigbo, the defense develops the affirmative story of good faith — and attacks the gaps in the State's circumstantial chain.
  6. Suppression and sourcing problems
    Custodial statements taken without warnings, claim files assembled in violation of the policy's own procedures, and chain-of-custody gaps in digital evidence are litigation targets before trial. The defense audits how the special-investigations-unit file was built, how the examination under oath was compelled, and whether any statement to law enforcement crossed the line into a custodial interrogation requiring Miranda warnings — then moves to suppress under Code Crim. Proc. art. 38.23 where the record supports it.
  7. Defective indictment — pleading and aggregation
    A document-driven charge must pin down the specific statement alleged to be false; a vague indictment that fails to identify it is vulnerable to a motion to quash. Separately, § 35.03 lets the State combine claims under one scheme either by aggregating the values or, with three or more claims, bumping the grade — but the two mechanisms are mutually exclusive, so an indictment that stacks both has a defect worth litigating. The defense scrutinizes the charging instrument before the first setting.
Defense Timeline

How we build the case

Texas insurance fraud defense follows a predictable four-phase arc — pre-charge investigation and counsel, then discovery and claim-file audit, then motion practice and plea negotiation, then trial readiness or resolution.

  1. Pre-charge
    Investigation, counsel, valid-loss documentation
    Retain counsel before speaking with the carrier's special investigations unit; invoke the Fifth Amendment before any recorded statement or examination under oath; map the claim back to its source documents — proof of loss, estimates, invoices, recorded calls — and separate what the client said from what a contractor, public adjuster, or billing clerk prepared; begin documenting the legitimate covered loss for the § 35.02(g) valid-portion fight; where charges have not yet been filed, prepare a pre-indictment presentation to the screening prosecutor and, if needed, arrange a walk-through surrender.
  2. Day 0-60
    Discovery, claim-file audit, expert work
    Article 39.14 discovery reaching the entire claim file, the special-investigations-unit workup, and the referral packet; audit of the charged "statement" and the materiality theory; forensic accounting on value and aggregation under § 35.03; estimator review of scope of loss; origin-and-cause analysis in any companion arson matter; preliminary analysis of knowledge, intent, and any suppression issues arising from compelled or custodial statements.
  3. Month 2-6
    Motion practice and plea negotiation
    Motion to quash where the indictment fails to pin down a specific false statement; motion to suppress custodial statements taken without warnings; challenge to an indictment that improperly stacks aggregation under § 35.03; valid-portion litigation under § 35.02(g) and Florez v. State; plea negotiation including grade reduction, pretrial diversion for first-time financial offenses where available, deferred adjudication structure, and non-disclosure planning under Tex. Govt. Code § 411.072.
  4. Month 6+
    Trial readiness or resolution
    Document-driven bench or jury trial on the five claim elements — qualifying statement, falsity, materiality under § 35.015, knowledge, and intent to defraud — presented through fact witnesses, forensic accountants, and estimators; jury instructions on the valid-portion offset where supported; restitution posture under § 35.02(e) addressed early; immigration-consequence analysis under Padilla v. Kentucky before any plea given the moral-turpitude and aggravated-felony exposure; nondisclosure planning where a deferred-adjudication discharge is achieved.

Investigated or charged with insurance fraud in Collin, Denton, Dallas, or Tarrant County?

L and L Law Group defends insurance fraud cases at every grade — claim, application, and provider-kickback — from a fine-only misdemeanor through a first-degree felony. Free initial consultation.

Call (972) 370-5060

Frequently asked questions

The questions we answer most often about Texas insurance fraud cases — how the grade is set, whether an unpaid claim is chargeable, what the State must prove, the valid-portion defense, talking to investigators, how cases start, record-clearing, provider exposure, and collateral consequences.

Is insurance fraud a felony in Texas?

It depends on the value of the fraudulent claim. Penal Code § 35.02 grades insurance fraud on the same dollar ladder as theft, from a Class C misdemeanor under $100 up to a first-degree felony at $300,000 or more. Application fraud is a state jail felony at any amount, and any act that risks death or serious bodily injury is a first-degree felony regardless of the dollar figure.

Can I be charged with insurance fraud if the insurer never paid the claim?

Yes. Payment is not an element of Penal Code § 35.02. The offense is complete when a knowingly false, material statement is prepared or presented to an insurer with intent to defraud, so a denied, withdrawn, or still-pending claim can be charged the same as a paid one. That the carrier lost no money is not a legal defense, though it matters in negotiation.

What does the State have to prove for Texas insurance fraud?

For a claim count under § 35.02(a), the State must prove a statement made to an insurer, that the statement was false or misleading, that the false information was material, that the accused knew it was false, and that the accused intended to defraud or deceive the insurer. Intent is the element most cases turn on, and it is almost always proven by circumstantial evidence rather than a confession.

What is the "valid portion" defense in an insurance fraud case?

Under § 35.02(g), if you prove by a preponderance of the evidence that part of a claim came from a genuine covered loss, the "value of the claim" that sets the punishment grade is only the fraudulent difference, not the gross amount submitted. A Fort Worth appellate court confirmed this means the fraudulent portion only. Documenting the legitimate loss can pull a felony grade down a level and change probation and record-sealing eligibility.

Should I talk to the insurance company's investigator?

Not before you speak with a defense lawyer. A recorded statement, an examination under oath, or a portal entry is itself a "statement" under § 35.01(3) and can become the State's key exhibit. Texas appellate courts have held that a defendant's own recorded statements to an adjuster are admissible and do not raise Confrontation Clause problems. What feels like cooperation often builds the case.

How do insurance fraud cases usually start in North Texas?

Rarely with an arrest at the scene. A claim trips an insurer's special investigations unit, which compiles recorded interviews and inspections, then refers the file to the Texas Department of Insurance Fraud Unit or the county. Months later the first sign of trouble is an investigator's card, a grand jury subpoena, or a warrant notice. That pre-charge gap is often the strongest window to involve counsel.

Can an insurance fraud charge be dismissed or kept off my record?

Sometimes. Early advocacy can show a screening prosecutor that the "lie" was an estimate or that the materiality theory is thin, and some North Texas counties run pretrial diversion for first-time financial offenses that ends in dismissal. A dismissal or acquittal can support expunction; a deferred-adjudication discharge may support nondisclosure. A final felony conviction forecloses both.

I run a clinic or body shop — can I be charged without making a false statement?

Yes. Subsection (b) of § 35.02 reaches anyone who solicits, offers, pays, or receives a benefit in connection with goods or services billed to an insurer. No false statement is required — the kickback itself is the offense. Providers also face a rebuttable presumption under § 35.02(h) that whoever submitted a bill caused the claim to be presented, which is why provider cases defend differently from policyholder cases.

What are the collateral consequences of an insurance fraud conviction?

Because it is a crime of dishonesty, the fallout reaches beyond any sentence. Licensed agents, adjusters, and medical providers face board discipline; a felony costs firearm rights under Penal Code § 46.04 and federal law; and for non-citizens, fraud is a crime involving moral turpitude that, with a loss over $10,000, can be an aggravated felony for immigration purposes. Employment screening, civil suits, and industry claim databases add to the tail.

References

All citations link to statutes.capitol.texas.gov for primary text. Footnote numbers in the body link here; the arrow returns to the citing paragraph.

  1. Tex. Penal Code § 35.02 — Insurance fraud (and §§ 35.01, 35.015, 35.03, 35.04).
  2. Tex. Insurance Code ch. 701 — Fraud investigations and referral.
  3. Tex. Penal Code § 46.04 — Unlawful possession of firearm (felony firearm-rights loss).
  4. Florez v. State, No. 02-16-00195-CR (Tex. App.—Fort Worth June 8, 2017, no pet.) (mem. op.) — value of the claim is the fraudulent portion only under § 35.02(g).
  5. Obigbo v. State, 6 S.W.3d 299 (Tex. App.—Dallas 1999, pet. ref'd) — broad reading of "statement"; intent proven by circumstantial evidence.
  6. Tex. Code Crim. Proc. art. 38.23 — Suppression of unlawfully obtained evidence.
  7. Tex. Code Crim. Proc. art. 39.14 — Michael Morton Act discovery (reaches the full claim file).
  8. Texas Department of Insurance — Fraud Unit — state fraud-investigation authority.
40+
Years
Combined defense experience
$0
Consult
Free initial consultation
24/7
Available
Direct-to-attorney for jail release
About the authors

The attorneys behind this page

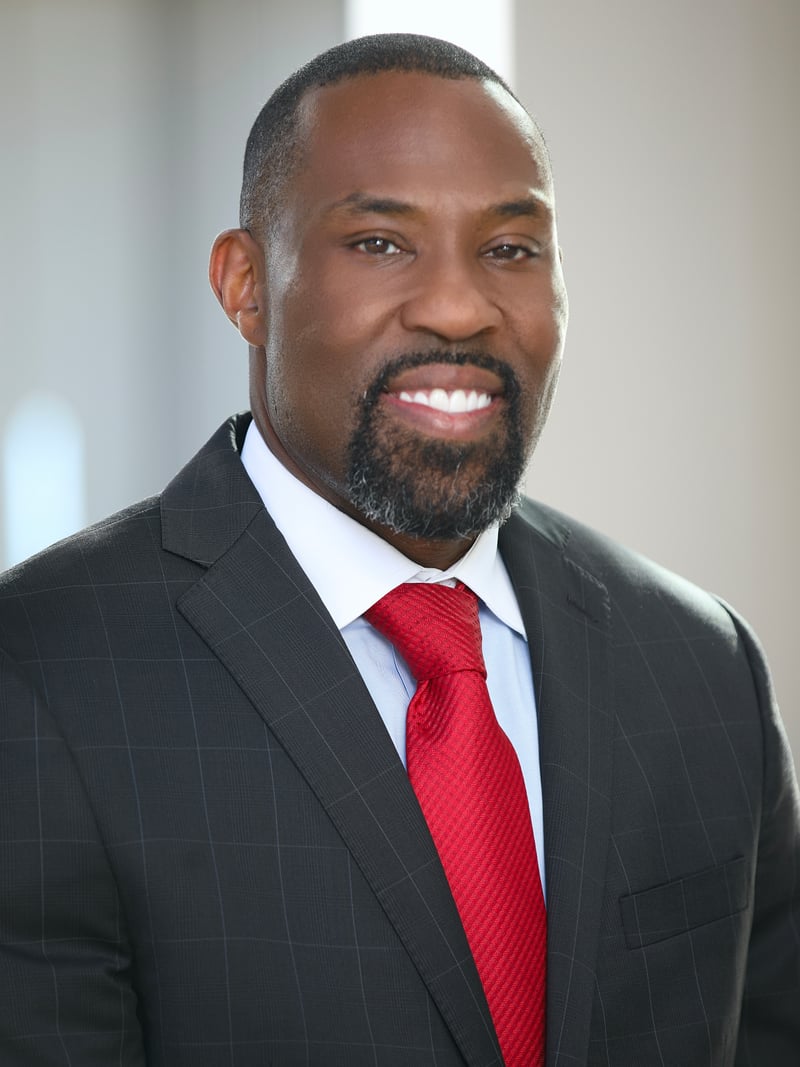
Reggie London

Reggie London

Co-Founding Partner · Criminal Defense Attorney

Admitted in Texas, TXND, TXED, and the U.S. Court of Appeals for the Fifth Circuit. Practice spans DWI, drug, weapons, theft, and process crimes — plus federal practice.

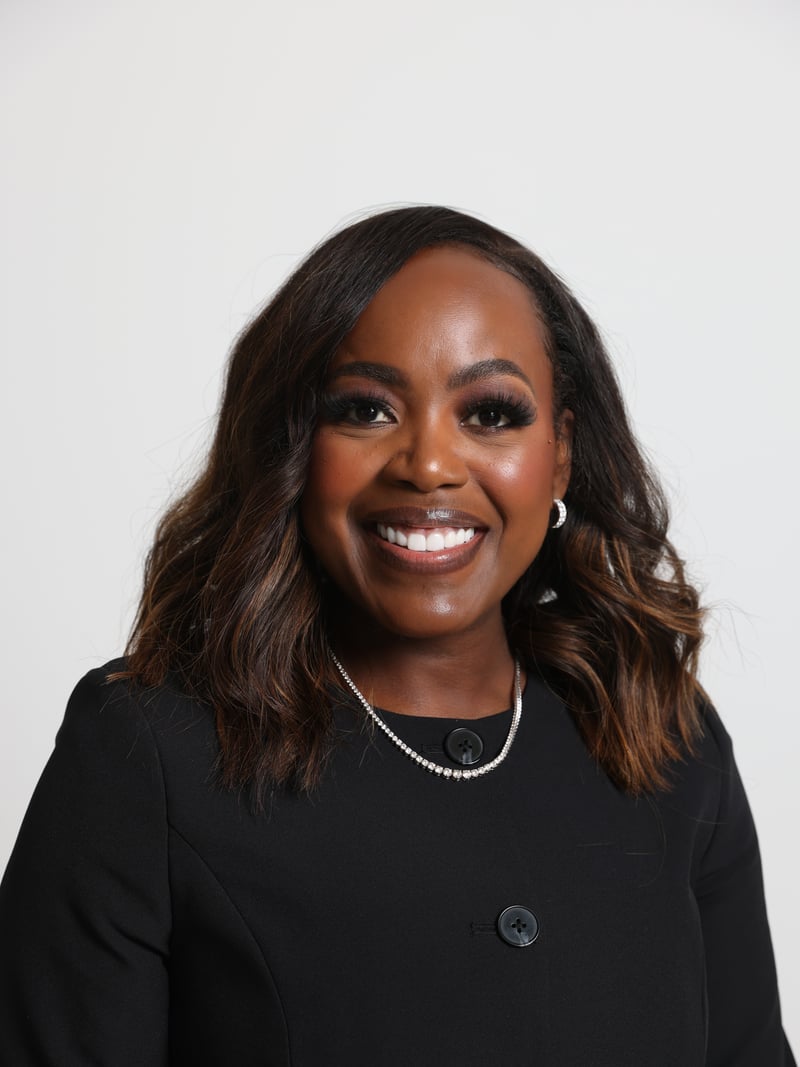
Njeri London

Njeri London

Co-Founding Partner · Criminal Defense Attorney

Texas-licensed criminal defense attorney with deep Fourth Amendment motion practice. Focus: suppression hearings, drug-crime defense, federal-practice support.

From the blog

Related writing on this topic

Free Consultation · 24/7

Talk to an attorney — not a screener.

Tell us about your case. Most clients hear back within an hour. Often within minutes.

5899 Preston Rd, Ste 101 · Frisco, TX 75034

By submitting, you agree to our Privacy Policy.

Call (972) 370-5060

Attorney Advertising

This website is for general information purposes only and constitutes attorney advertising under the Texas Disciplinary Rules of Professional Conduct. Nothing on this site should be taken as legal advice for any individual case or situation. Receipt or viewing does not create an attorney–client relationship.

Past results do not guarantee similar outcomes. Each case is unique and must be evaluated on its own facts and circumstances.

L and L Law Group, PLLC attorneys are licensed to practice in the State of Texas. Njeri London (Texas Bar No. 24043266) and Reggie London (Texas Bar No. 24043514) are the attorneys responsible for the content of this site. None of the attorneys at L and L Law Group, PLLC are Board Certified by the Texas Board of Legal Specialization unless specifically and separately stated.

Please do not transmit any confidential information to L and L Law Group, PLLC by email, web form, or telephone before a written engagement is in place. Privacy Policy.

Service Areas

L&L Law Group represents clients across North Texas counties for DWI, assault, drug crimes, juvenile defense, outstanding warrants, bond reduction, and expunction matters.

Call Email Map Top
developed by MPR Digital Legal Services